Who Tends to Need a $1,500 Loan
A $1,500 loan, like most mid-size personal loans, usually goes to homeowners, renters in transition and patients facing a bill after insurance. These borrowers typically have steady income and some savings, but not enough to absorb a cost that runs into four figures without disrupting regular bills.
At this amount the profile shifts slightly from smaller requests. The cost behind these personal loans is often tied to housing or health, and it frequently arrives with a quote or invoice rather than as a vague shortfall. A homeowner in her 50s whose air conditioner fails during a heat wave, a couple signing a lease that requires a deposit plus first month's rent, and a patient who received an outpatient bill after meeting a high deductible all fit here.
People searching for a 1500 dollar loan also tend to think in terms of a monthly budget line rather than a lump sum. They ask: what will this add to my month, and for how long? A fixed-rate personal loan answers both questions on day one, which is a large part of its appeal over a credit card that sets a minimum payment and leaves the payoff date open.
Repayment Term Options for a $1,500 Loan
Terms of 6, 12 and 18 months are the most common starting points for a $1,500 loan, and the choice mostly depends on how much of your monthly budget you can commit. Twelve months is a frequent balance between payment size and total interest.
The cards below give estimated payments for each of those terms on a fixed-rate personal loan. They are planning figures only; the lender's offer will show the actual APR, any fees and the exact schedule.
Representative example: $1,500 borrowed over 12 months at 24% APR works out to about $141.84 a month, or about $1,702.07 in total (estimate only; your lender's offer may differ). Six months at the same APR raises the payment to about $267.79 but saves close to $100 in interest compared with 12 months.
At this amount, an 18-month term becomes more practical than it is for smaller loans, because the payment drops to about $100.05 at 24% APR. That relief costs about $300.96 in estimated interest, so weigh it against what you can comfortably handle. The personal loan calculator lets you plug in other terms and rates.
How to Size Your Request Before Borrowing $1,500
The right size for a $1,500 loan is the written quote for the job, minus any savings you can safely use, plus nothing for extras. Rounding up out of caution adds interest you will repay for every month of the term.
Sizing well starts with documents, not guesses, and it is the step most often skipped on personal loans. Use this short worksheet:
- Get the quote in writing. Contractors, movers and medical billing offices can all provide an itemized estimate.
- Ask about a cash or prompt-pay discount. Some providers trim several percent for payment in full.
- Subtract what savings can cover while still leaving a small cushion for the month.
- Check the timing. If part of the cost is due later, such as a final moving payment, you may not need to borrow it today.
- Request the result. If the number lands at $1,200, request $1,200 rather than a round $1,500.
Because our form accepts requests from $500 to $5,000, you can enter an exact figure. A tighter request also helps lenders evaluate your application, a point that applies to any leap credit loan request; a personal loan that matches a documented cost is easy to explain.
Three Common Reasons Borrowers Choose $1,500
A $1,500 loan typically funds home system repairs, moving and deposit costs, and medical or dental balances after insurance. Each brings its own timing pressure, documents and cheaper alternatives worth comparing first.
Air Conditioning or Furnace Repair
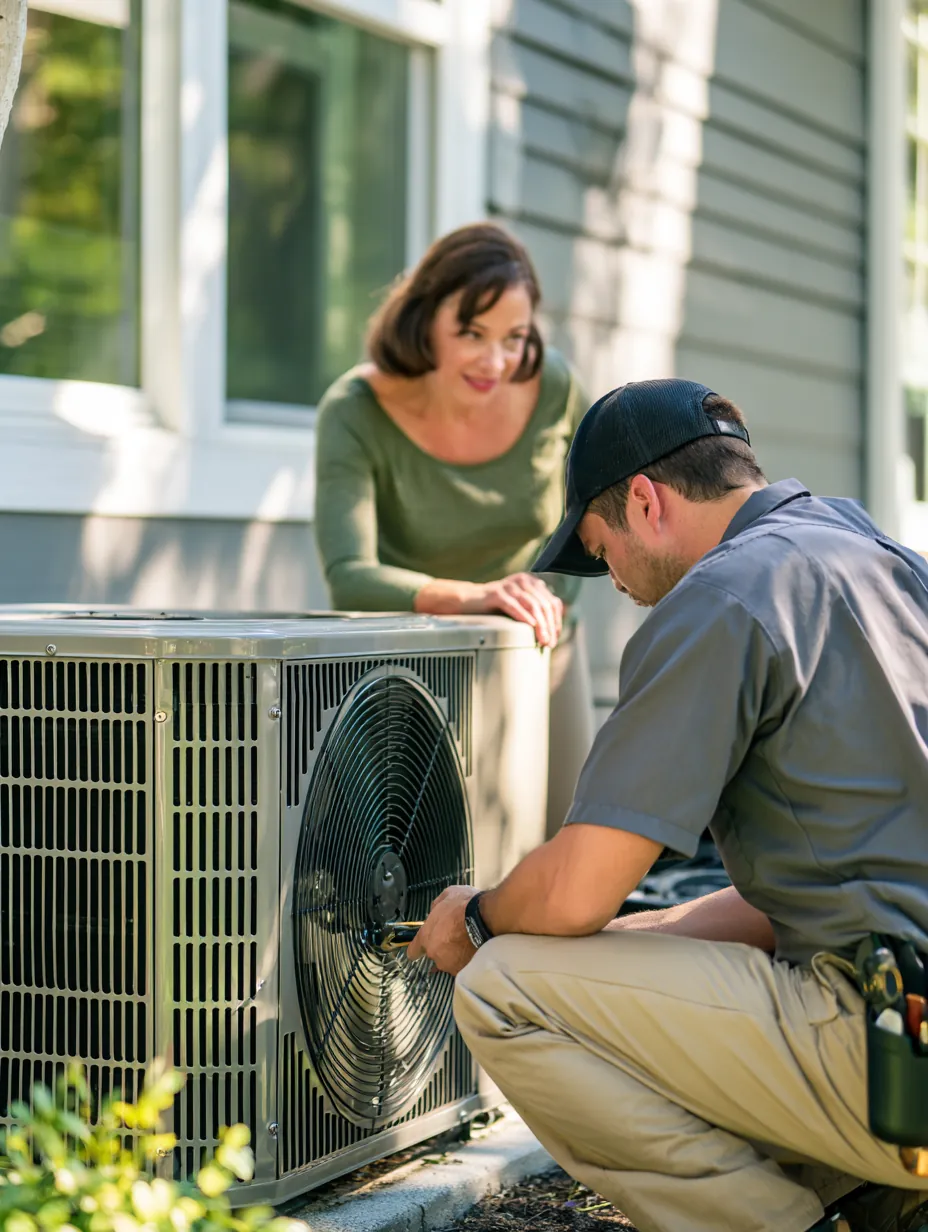
When a compressor, blower motor or capacitor fails in peak season, a repair visit with parts can easily reach this range. Picture a homeowner in her 50s watching a technician diagnose the outdoor unit on a hot afternoon. Waiting weeks to save is not realistic, especially for anyone with health conditions sensitive to heat. Ask the HVAC company whether it offers financing, then compare that rate with personal loan offers before choosing. Shoppers weighing leap credit loan options against in-house financing should line up the APR on each.
Moving Into a New Apartment
A security deposit, first month's rent, a truck rental and utility setup fees arrive all at once, often before the deposit on the old place is returned. For a young couple carrying boxes into a new building, a 1500 dollar loan can bridge the weeks until that refund arrives, after which a lump-sum payoff may be possible if the lender allows it without penalty.
Medical or Dental Balance After Insurance
High-deductible health plans can leave patients owing a meaningful balance after a procedure. Before turning to a personal loan, request an itemized bill, ask about financial assistance and check for billing errors. Our guide to medical loans covers how to approach these conversations and when borrowing makes sense.
Estimated $1,500 Loan Payments at Common APRs
Estimated monthly payments on a $1,500 loan range from about $74.89 (24 months at 18%) to about $276.89 (6 months at 35.99%). Shorter terms and lower APRs reduce total cost; longer terms trade lower payments for more interest.
| APR | 9 months | 12 months | 18 months | 24 months |
|---|---|---|---|---|
| 18% | about $179.41 | about $137.52 | about $95.71 | about $74.89 |
| 24% | about $183.77 | about $141.84 | about $100.05 | about $79.31 |
| 30% | about $188.19 | about $146.23 | about $104.51 | about $83.87 |
| 35.99% | about $192.64 | about $150.69 | about $109.06 | about $88.56 |
The estimated total repaid shows the long-run cost more clearly:
| APR | Est. total repaid, 12 months | Est. total repaid, 24 months | Extra cost of the longer term |
|---|---|---|---|
| 18% | about $1,650.24 | about $1,797.27 | about $147.03 |
| 24% | about $1,702.07 | about $1,903.36 | about $201.29 |
| 35.99% | about $1,808.23 | about $2,125.52 | about $317.29 |
All figures are estimates for a fixed-rate personal loan with no fees. At 35.99% over 24 months, total interest reaches about $625.52, or more than 40% of the amount borrowed. Our guide to personal loan rates explains how origination fees and APR combine, and shoppers comparing leap credit rates should look at the total repaid before the monthly figure.
Why a $1,500 Loan Works Well as an Installment Loan
A $1,500 loan is well suited to installment structure because the balance is large enough that paying it down over a set schedule beats carrying it on a card, yet small enough to finish within one to two years.
Installment personal loans give you the same payment every month and a fixed payoff date, which is why people searching leap credit installment options often land on this amount. Credit cards, by contrast, let the balance linger while interest accrues on whatever remains. On a $1,500 balance, paying only a card's minimum could stretch repayment for years.
| Feature | Installment personal loan | Credit card balance |
|---|---|---|
| Payment amount | Fixed each month | Varies with balance and minimum |
| Payoff date | Set when you sign | Open-ended |
| Rate | Usually fixed for the term | Often variable |
| Temptation to add more | None; balance only falls | Available credit refills as you pay |
For a deeper look at how fixed schedules work, our hub on installment loans explains amortization in plain terms. For a smaller need, a $1,000 loan may cover it; if the quote keeps rising, a $2,000 loan may avoid a second request.
Lender Requirements and Paperwork at This Level
Lenders reviewing a $1,500 loan usually expect verifiable income, an active checking account, a government ID, a Social Security number and US residency. Many also look at your debt-to-income ratio more closely than they would on a $500 request.
The paperwork for personal loans at this size is familiar, but expect lenders to weigh affordability a bit more at this size:
- Income verification: recent pay stubs, a benefits statement, or tax documents and bank statements if you are self-employed
- Debt-to-income review: lenders compare existing monthly obligations with gross income, then factor in the new payment
- Banking history: an account in good standing, with regular deposits over several months
- Identity checks: a photo ID and Social Security number, plus a current address
Anyone checking leap credit requirements for this amount can find the full list on our eligibility page. For personal loans in this range, lenders may begin with a soft credit check, and a hard inquiry may follow if you accept an offer and proceed with that lender.
Submitting Your $1,500 Request
Submitting a request for a $1,500 loan takes about five minutes on our free form. You enter the amount and purpose, your income and contact details, and lenders in our network that want to offer a personal loan show their terms before you commit.
Some practical tips for this amount:
- Have your quote handy. Selecting a purpose such as home repair, moving or medical, and entering an exact amount, presents a clear picture.
- List all income you can document. Part-time or benefit income counts toward personal loans if you can verify it.
- Compare total cost across offers. A lower monthly payment over a longer term may cost more overall.
We are an independent loan-request connector, not a lender, and we are not affiliated with any lender, app or company that uses a similar name. Some visitors reach us after typing leapcredit into a search bar or researching leap credit reviews; our service is free and there is no obligation to accept an offer. If you accept, you sign directly with the lender, and many lenders can deposit funds as soon as the next business day after approval and signing.
Cheaper Paths to Check Before Taking $1,500
Before committing to a $1,500 loan or any personal loan of similar size, check for contractor or provider financing at 0%, hospital financial assistance, a security-deposit alternative, or a seasonal plan for year-end costs. Each can lower or remove the amount you need to borrow.
- Promotional contractor financing. Some HVAC companies and dental offices offer short interest-free periods. Read the terms: deferred-interest plans can charge back interest if the balance is not paid in full by the deadline.
- Hospital financial assistance. Nonprofit hospitals are required to maintain financial assistance policies, and eligibility often extends further up the income scale than people expect.
- Deposit alternatives. Some landlords accept deposit installments or a surety product instead of the full deposit upfront.
- Credit union personal loans. If you belong to a credit union, ask about its small personal loan rates; members sometimes qualify for lower APRs than online offers.
- Utility efficiency programs. Utilities in some areas offer rebates or on-bill financing for heating and cooling equipment.
If your $1,500 need is tied to gifts and travel at year-end, our guide to holiday loans explains how to plan seasonal spending so repayment wraps up before the next season starts.
Repaying $1,500 Without Strain
Repaying a $1,500 loan comfortably depends on setting the payment below about 10% of your monthly take-home pay, automating it, and having a plan for the month the payment feels tight. Responsible borrowing at this level is mostly about planning ahead.
A few practical steps keep personal loans on track:
- Build the payment into your budget before the first due date, not after.
- Schedule autopay a day or two after your paycheck lands so the funds are always there.
- Call the lender early if trouble appears. Many lenders have hardship options, but they work best when requested before a missed payment.
- Use windfalls wisely. A tax refund or the returned deposit from your old apartment can retire the loan early if prepayment carries no penalty.
Comparing leap credit loan options is worthwhile only if the final payment leaves room for groceries, gas and a small buffer. When the personal loan is paid off, consider keeping the same amount flowing into savings; after a year, you may have built a fund that covers the next repair outright.
Frequently Asked Questions
What credit score do I need for a $1,500 loan?
Lenders set their own standards, and there is no single minimum across our network. Applicants with fair credit often receive offers, though usually at higher APRs than borrowers with strong credit histories.
Is it better to finance an HVAC repair through the contractor or with a personal loan?
Compare both by APR and total cost. A true 0% contractor plan can be cheaper if you repay before it ends, while a fixed-rate personal loan avoids deferred-interest surprises.
Can I repay a 1500 dollar loan early when my old security deposit comes back?
Many lenders allow early payoff without a penalty, which cuts total interest. Confirm the prepayment terms in your loan agreement before signing.
How long does a $1,500 loan usually last?
Common terms run from 6 to 24 months. Twelve and 18 months are popular at this amount because the payment stays manageable without stretching interest too far.
